Construction Job Costing Explained
Construction Job Costing Explained

Key takeaways
Construction job costing shows what you’ve actually spent on a job compared to what you budgeted.
Field purchases can take weeks to show up on the job cost report, especially when accounting has to wait for card statements, receipts, and job codes.
That delay makes it harder for PMs to catch overruns while there’s still time to do something about them.
Closing the books faster helps, but the bigger opportunity is getting purchases onto the right job when the money is spent.
Your job cost report isn’t wrong. It’s late.
Every contractor knows what the job cost report should tell you: Are we making money? Are materials running over? Is this phase tracking against the estimate? Do we need to make a change before the job gets away from us?
But those decisions are only as good as the costs you can actually see.
A PM can pull up a job cost report showing materials 4% under budget without seeing the $11,000 in wire and conduit the crew bought over the last two weeks. The money is already gone, but it hasn’t hit the job yet.
Those charges are still on the card, waiting for receipts and job codes before accounting can assign them to the right job. By the time that $11,000 shows up in the report, the job may be weeks further along.
That’s the problem with construction job costing today: you’re making decisions about the job you’re running now with numbers from weeks ago.
What is construction job costing?
Construction job costing is how contractors keep track of what they’re spending on a job compared to what they budgeted.
Every cost gets tied back to a job and usually a cost code. That gives you the job cost report: what you budgeted, what you’ve actually spent, and where you’re over or under.
Most job costs fall into a few buckets:
Labor: Crew hours, trades, phases, and labor burden.
Materials: Everything from a lumber package to a quick run to the supply house.
Equipment: Owned equipment, rentals, fuel, and other equipment costs.
Subcontractors: Contracts, invoices, retainage, and what’s been billed so far.
Other direct costs: Permits, dumpsters, small tools, and everything else the field buys to keep the job moving.
For job costing to work, those costs need to be assigned to the right job. But they also need to get there soon enough to matter. The sooner you see where a job is running over, the more time you have to correct it.
So why do job costs show up weeks late?
Because field purchases often go through several steps before they ever reach the job cost report.
When a foreman buys $340 in fittings at the supply house, he already knows which job they’re for and why he needs them. But that information usually doesn’t travel with the purchase.
The card gets swiped, the receipt gets tossed in a pocket or truck, and the charge sits there until accounting sees it later. By then, someone has to track down the receipt and ask the field where the purchase belongs.
Step | What happens | When |
Card swipe | Foreman buys $340 in fittings at the supply house. | Day 0 |
Statement close | The charge sits on the card statement until the billing cycle ends. | End of billing cycle |
Receipt chase + coding | Accounting collects receipts, tracks down unlabeled charges, assigns jobs and cost codes, and enters the spend. | First days of the next month |
Month-end close | Reconciliation, accruals, WIP updates, and final cleanup happen. | About 8 days on average for construction firms surveyed |
The report | The purchase finally shows up against the job. | Often weeks after the money was spent |
Sage Intacct’s Close the Books research found construction firms averaged about eight days to close their books.
But that eight-day clock starts after the month is already over.
Take a purchase made August 20. If it gets fully reconciled around September 11, you’re looking at roughly three weeks between spend and visibility.
Make the purchase August 4? Same September report. Now you’re north of five weeks. And that’s when everything goes right. The receipt exists. Someone remembers the job. The foreman answers accounting’s text. Nobody throws the charge into overhead just to get the books closed.
Late job costs don’t just make accounting harder
They also make it harder to protect job margin.
Construction margins don’t leave much room for costs you didn’t see coming. CFMA’s 2025 Financial Benchmarker, based on financial statements from 1,558 companies, reported an average pretax margin of 6.7% for 2024. At that same percentage, $2 million in revenue would produce about $134,000 in pretax profit.
An $11,000 materials overrun might not sound huge on a $2 million job. But against $134,000 in pretax profit, it’s more than 8%. And that’s one overrun on one job.
When costs stay hidden for weeks, small misses can pile up before anyone realizes the job is off track. By the time they hit the job cost report, the question isn’t how to prevent them. It’s how much margin they already took with them.
Bad data doesn't have to be wrong
Late data can cause just as much trouble.
Autodesk and FMI define bad construction data as inaccurate, incomplete, inaccessible, inconsistent, or untimely. Their research estimated that bad data may have cost the global construction industry $1.85 trillion in 2020.
A $5,000 purchase can be assigned to the right job and still cause a problem if the PM doesn’t see it for a month. By then, the crew may have kept buying the same materials, the job may be nearly finished, and the budget may already be blown. The number is accurate, but it showed up too late to change anything.
Then accounting has to track it all down
When a field purchase isn’t tied to a job and cost code, accounting has to figure it out later.
That means tracking down receipts, figuring out who made the purchase, asking which job it was for, and getting the right cost code. And they’re usually asking someone in the field who has made dozens of purchases since then and is busy running a job.
That back-and-forth adds up. Autodesk’s 2025 construction research found that people across construction organizations spend an average of 13 hours a week just looking for the data they need to do their jobs.
Not all of that is spent chasing receipts and job codes, but the problem is the same: information exists somewhere. Someone just has to stop what they’re doing and go find it.
It’s extra work on both sides that could have been avoided if the job, cost code, and receipt had been captured when the purchase happened.
Mystery charges create another problem: bad cost history
When accounting can’t figure out which job a field purchase belongs to, the charge still has to go somewhere. Sometimes it ends up in overhead just to close the books.
That creates a bigger problem. The job looks like it cost less than it actually did, while overhead looks higher. Then, when the estimator uses that job as a reference for the next bid, they’re working from the wrong numbers.
A few hundred dollars here and there might not seem like much. But across dozens of purchases, multiple crews, and multiple jobs, those missing costs add up — and can make a job look more profitable than it really was.
Now you’re not just missing costs on the job you finished. You’re using bad numbers to price the next one.
Why a faster month-end close doesn’t solve the whole problem
There’s plenty contractors can do to close the books faster: better processes, easier reconciliation, clearer responsibilities, and more automation. All of it helps.
But a faster close only speeds up what happens at month-end. It doesn’t fix the weeks before that, when field purchases are being made but haven’t made it onto the job yet.
The easiest time to get the right information is when the purchase happens. The person buying the material already knows which job it’s for and has the receipt in hand. If you capture the job, cost code, and receipt right then, accounting doesn’t have to track it all down weeks later.
That’s the bigger opportunity: get the cost onto the right job when the money is spent, instead of waiting until month-end to sort it out.
What real-time job costing looks like
Real-time job costing means getting field purchases onto the right job as close to the time of purchase as possible, instead of waiting until the end of the month to sort them out.
Here’s what that looks like in practice:
Assign the job when the purchase happens.
The person making the purchase already knows which job it’s for. Have them select the job when they spend the money so accounting doesn’t have to figure it out later.
Get the receipt right away.
Take a photo when the purchase is made instead of trying to track down a paper receipt weeks later.
Make cost coding simple for the field.
A foreman shouldn’t have to search through hundreds of cost codes to find the right one. Give them the codes that actually apply to their job and the work they’re doing.
Give each person their own card.
When cards are shared, accounting has to figure out who made each purchase. Individual cards make it clear who spent the money and who to ask if something is missing.
Send purchases to the accounting system as they happen.
Accounting shouldn’t have to wait for the card statement to see what was spent. Transactions should flow into the accounting system throughout the month, with the job, cost code, and receipt already attached.
Check job costs throughout the month.
When PMs can see current costs against the budget, they can catch overruns earlier and make changes while there’s still work left to do.
Handle spend while it’s still happening
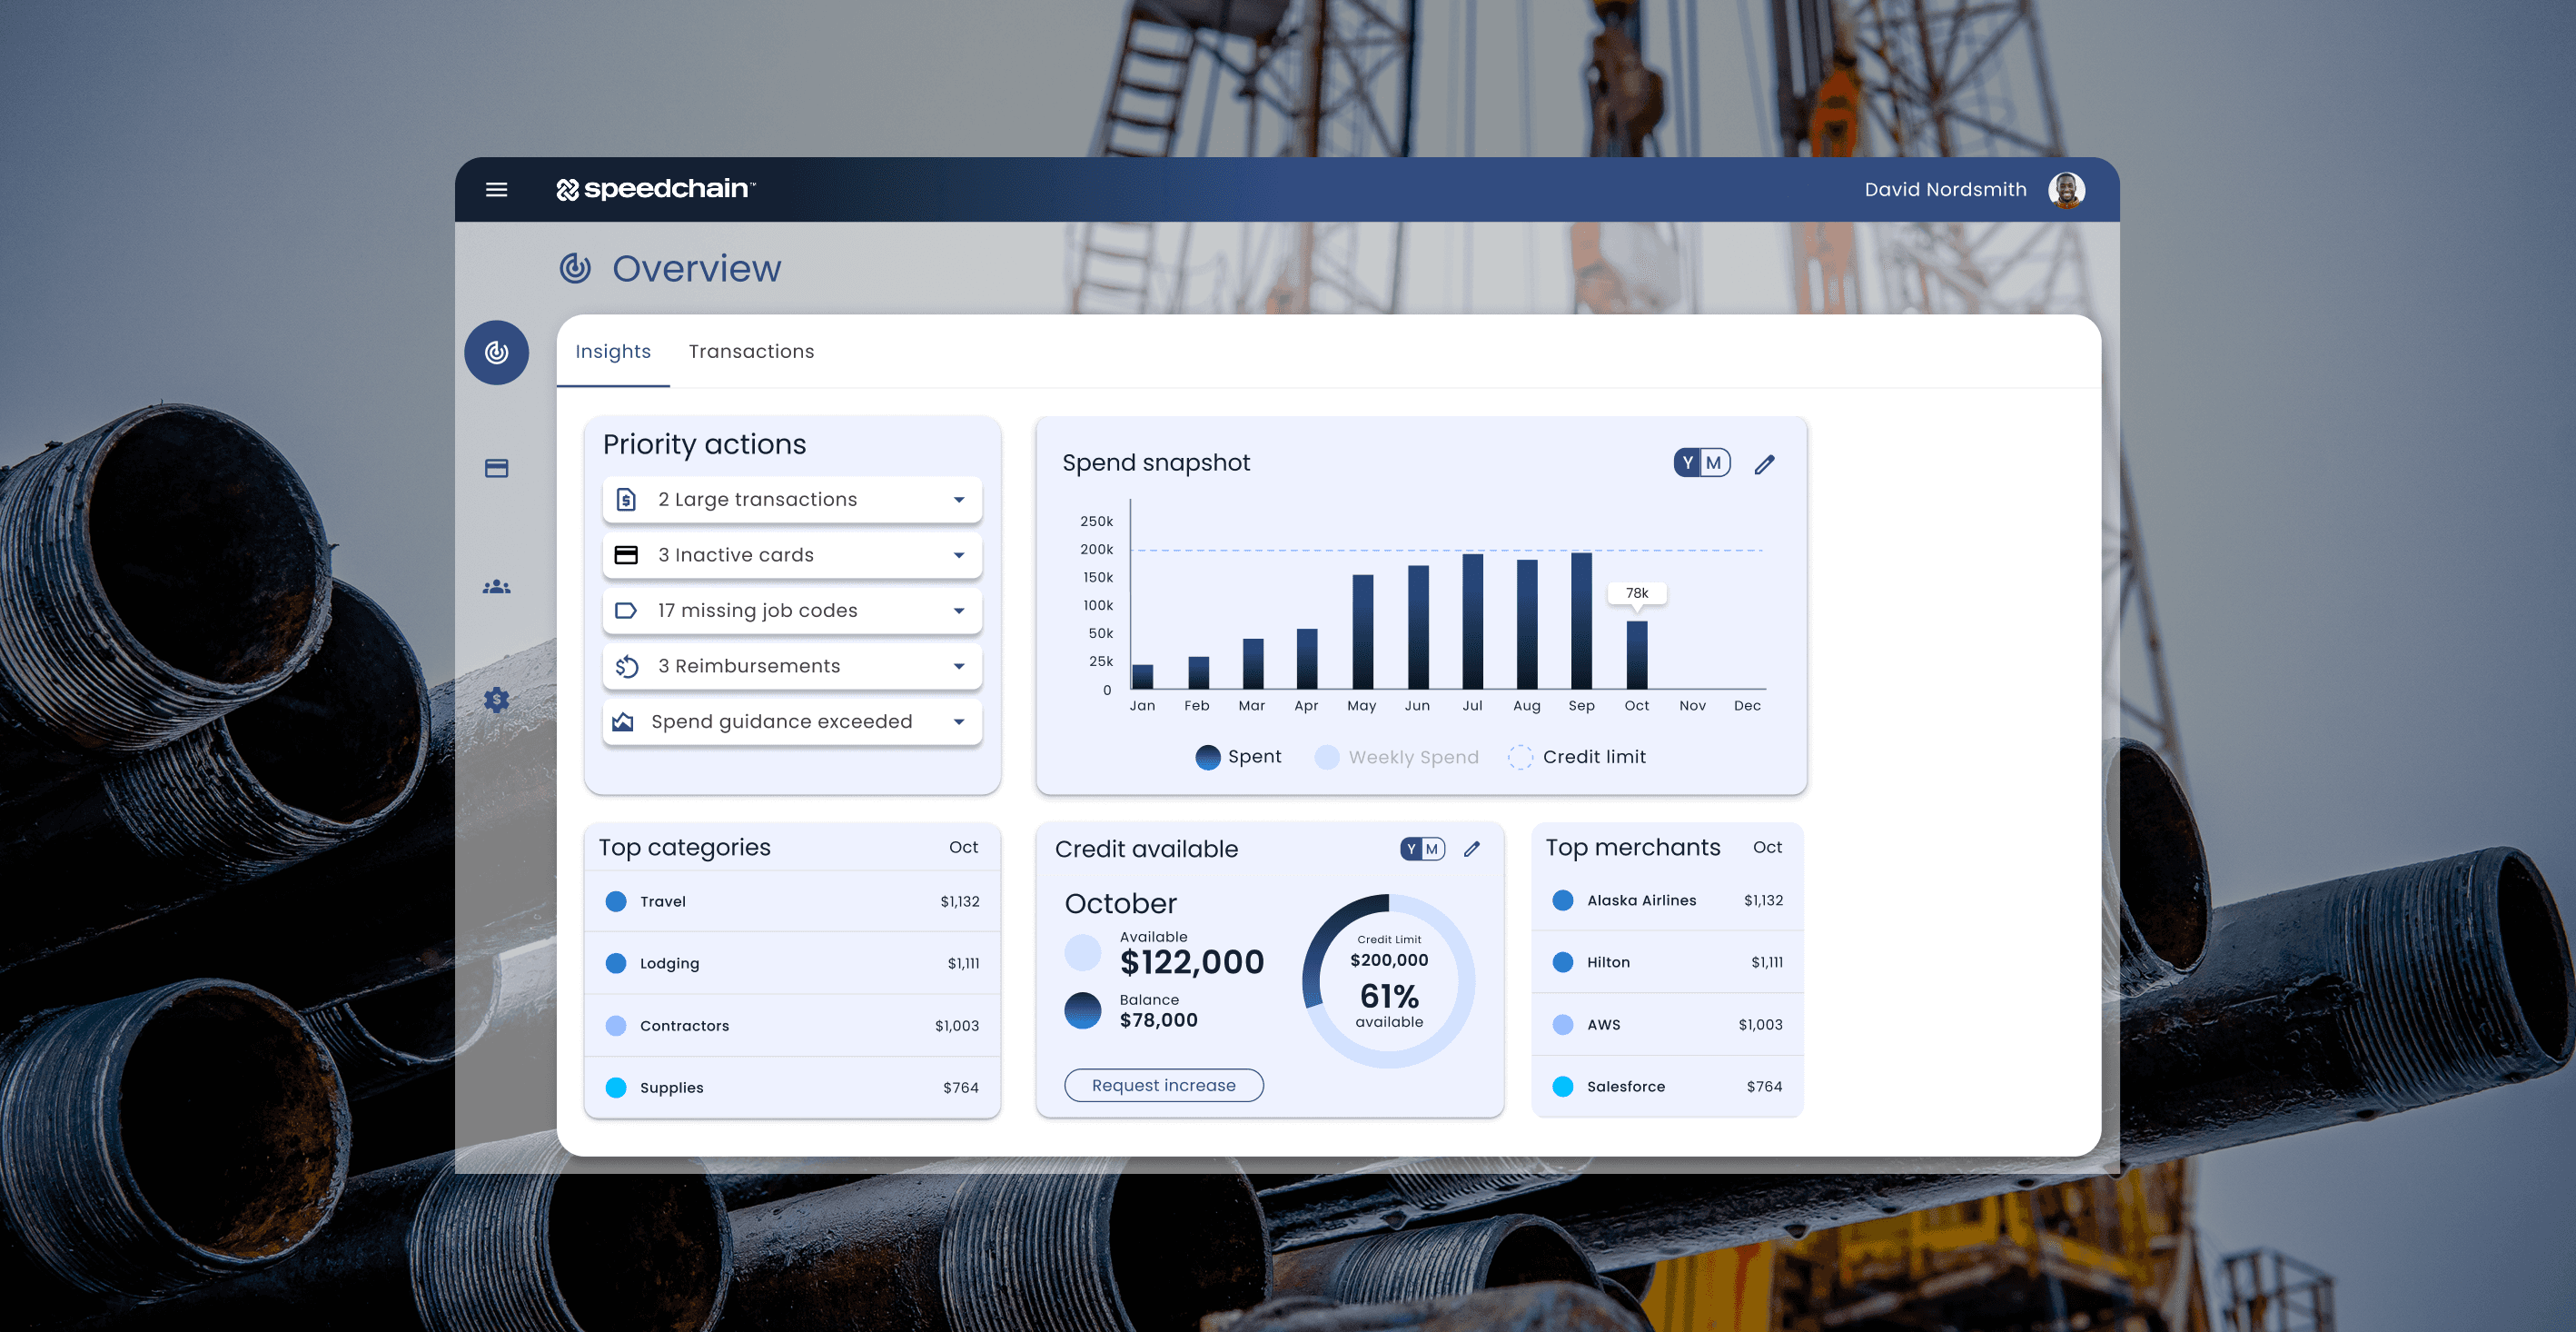
Speedchain combines commercial cards with construction-specific spend controls so the job, cost code, and receipt can be captured when the purchase happens.
That information then moves into the accounting system your team already uses, including Sage Intacct, Sage 300 CRE, QuickBooks Desktop, Spectrum, Viewpoint Vista, Acumatica, and other construction accounting systems.
Accounting spends less time tracking down missing information, and PMs get a more current view of what’s actually being spent on their jobs.
For O’Brien Construction, moving field spend to Speedchain helped cut month-end close time by 60%.
For job costing to work, those costs need to be assigned to the right job. But they also need to get there soon enough to matter. The sooner you see where a job is running over, the more time you have to correct it.
So why do job costs show up weeks late?
Because field purchases often go through several steps before they ever reach the job cost report.
When a foreman buys $340 in fittings at the supply house, he already knows which job they’re for and why he needs them. But that information usually doesn’t travel with the purchase.
The card gets swiped, the receipt gets tossed in a pocket or truck, and the charge sits there until accounting sees it later. By then, someone has to track down the receipt and ask the field where the purchase belongs.
Step | What happens | When |
Card swipe | Foreman buys $340 in fittings at the supply house. | Day 0 |
Statement close | The charge sits on the card statement until the billing cycle ends. | End of billing cycle |
Receipt chase + coding | Accounting collects receipts, tracks down unlabeled charges, assigns jobs and cost codes, and enters the spend. | First days of the next month |
Month-end close | Reconciliation, accruals, WIP updates, and final cleanup happen. | About 8 days on average for construction firms surveyed |
The report | The purchase finally shows up against the job. | Often weeks after the money was spent |
Sage Intacct’s Close the Books research found construction firms averaged about eight days to close their books.
But that eight-day clock starts after the month is already over.
Take a purchase made August 20. If it gets fully reconciled around September 11, you’re looking at roughly three weeks between spend and visibility.
Make the purchase August 4? Same September report. Now you’re north of five weeks. And that’s when everything goes right. The receipt exists. Someone remembers the job. The foreman answers accounting’s text. Nobody throws the charge into overhead just to get the books closed.
Late job costs don’t just make accounting harder
They also make it harder to protect job margin.
Construction margins don’t leave much room for costs you didn’t see coming. CFMA’s 2025 Financial Benchmarker, based on financial statements from 1,558 companies, reported an average pretax margin of 6.7% for 2024. At that same percentage, $2 million in revenue would produce about $134,000 in pretax profit.
An $11,000 materials overrun might not sound huge on a $2 million job. But against $134,000 in pretax profit, it’s more than 8%. And that’s one overrun on one job.
When costs stay hidden for weeks, small misses can pile up before anyone realizes the job is off track. By the time they hit the job cost report, the question isn’t how to prevent them. It’s how much margin they already took with them.
Bad data doesn't have to be wrong
Late data can cause just as much trouble.
Autodesk and FMI define bad construction data as inaccurate, incomplete, inaccessible, inconsistent, or untimely. Their research estimated that bad data may have cost the global construction industry $1.85 trillion in 2020.
A $5,000 purchase can be assigned to the right job and still cause a problem if the PM doesn’t see it for a month. By then, the crew may have kept buying the same materials, the job may be nearly finished, and the budget may already be blown. The number is accurate, but it showed up too late to change anything.
Then accounting has to track it all down
When a field purchase isn’t tied to a job and cost code, accounting has to figure it out later.
That means tracking down receipts, figuring out who made the purchase, asking which job it was for, and getting the right cost code. And they’re usually asking someone in the field who has made dozens of purchases since then and is busy running a job.
That back-and-forth adds up. Autodesk’s 2025 construction research found that people across construction organizations spend an average of 13 hours a week just looking for the data they need to do their jobs.
Not all of that is spent chasing receipts and job codes, but the problem is the same: information exists somewhere. Someone just has to stop what they’re doing and go find it.
It’s extra work on both sides that could have been avoided if the job, cost code, and receipt had been captured when the purchase happened.
Mystery charges create another problem: bad cost history
When accounting can’t figure out which job a field purchase belongs to, the charge still has to go somewhere. Sometimes it ends up in overhead just to close the books.
That creates a bigger problem. The job looks like it cost less than it actually did, while overhead looks higher. Then, when the estimator uses that job as a reference for the next bid, they’re working from the wrong numbers.
A few hundred dollars here and there might not seem like much. But across dozens of purchases, multiple crews, and multiple jobs, those missing costs add up — and can make a job look more profitable than it really was.
Now you’re not just missing costs on the job you finished. You’re using bad numbers to price the next one.
Why a faster month-end close doesn’t solve the whole problem
There’s plenty contractors can do to close the books faster: better processes, easier reconciliation, clearer responsibilities, and more automation. All of it helps.
But a faster close only speeds up what happens at month-end. It doesn’t fix the weeks before that, when field purchases are being made but haven’t made it onto the job yet.
The easiest time to get the right information is when the purchase happens. The person buying the material already knows which job it’s for and has the receipt in hand. If you capture the job, cost code, and receipt right then, accounting doesn’t have to track it all down weeks later.
That’s the bigger opportunity: get the cost onto the right job when the money is spent, instead of waiting until month-end to sort it out.
What real-time job costing looks like
Real-time job costing means getting field purchases onto the right job as close to the time of purchase as possible, instead of waiting until the end of the month to sort them out.
Here’s what that looks like in practice:
Assign the job when the purchase happens.
The person making the purchase already knows which job it’s for. Have them select the job when they spend the money so accounting doesn’t have to figure it out later.
Get the receipt right away.
Take a photo when the purchase is made instead of trying to track down a paper receipt weeks later.
Make cost coding simple for the field.
A foreman shouldn’t have to search through hundreds of cost codes to find the right one. Give them the codes that actually apply to their job and the work they’re doing.
Give each person their own card.
When cards are shared, accounting has to figure out who made each purchase. Individual cards make it clear who spent the money and who to ask if something is missing.
Send purchases to the accounting system as they happen.
Accounting shouldn’t have to wait for the card statement to see what was spent. Transactions should flow into the accounting system throughout the month, with the job, cost code, and receipt already attached.
Check job costs throughout the month.
When PMs can see current costs against the budget, they can catch overruns earlier and make changes while there’s still work left to do.
Handle spend while it’s still happening
Speedchain combines commercial cards with construction-specific spend controls so the job, cost code, and receipt can be captured when the purchase happens.
That information then moves into the accounting system your team already uses, including Sage Intacct, Sage 300 CRE, QuickBooks Desktop, Spectrum, Viewpoint Vista, Acumatica, and other construction accounting systems.
Accounting spends less time tracking down missing information, and PMs get a more current view of what’s actually being spent on their jobs.
For O’Brien Construction, moving field spend to Speedchain helped cut month-end close time by 60%.

Frequently asked questions
What is job costing in construction?
Construction job costing is how contractors track what they actually spend on a job against what they budgeted. That includes labor, materials, equipment, subcontractors, and field purchases. Those costs are assigned to the right job and cost code so you can see where the money is going and whether the job is on budget.
What is the difference between job costing and job cost coding?
Job costing is the bigger picture: what have we spent on this job compared to what we budgeted?
Job cost coding is how you organize those costs. Each expense gets assigned to the right job, phase, and type of work so you know where the money went.
Why is my job cost report always behind?
Many field purchases don’t get assigned to the job when the money is spent. The charge may sit on a card until the statement closes, while accounting waits for the receipt and figures out the right job and cost code.
By the time everything is entered and reconciled, the purchase may be several weeks old.
How long does month-end close take for construction companies?
In Sage Intacct’s 2020 Close the Books survey, construction firms surveyed averaged eight days to close their books.
But that’s eight days after the month ends. If a field purchase was made early in the month and doesn’t get processed until close, it could be several weeks old before it shows up in the final numbers.
How do construction companies track job costs in real time?
The key is to get the purchase onto the right job when it happens. For field spending, that means selecting the job and cost code when the card is used, capturing the receipt right away, and sending that information to the accounting system throughout the month.
That way, PMs can see what’s being spent without waiting until month-end, and accounting has less to track down later.
Which costs belong on a job and which go to overhead?
If the cost was for a specific job, it should generally be charged to that job. That includes materials, subcontractors, equipment, and smaller field purchases.
Overhead covers costs that support the business as a whole, like office rent and administrative salaries.
When someone puts a field purchase into overhead simply because no one knows which job it belongs to, the numbers get skewed. Overhead looks higher, and the job looks more profitable than it really was.